
Most financial services firms are doing something in digital.
They have a website, they send emails, and they post on social media. They may be investing in SEO, paid search, content marketing or marketing automation.
So when I talk to an executive about improving digital growth, the initial reaction can sometimes be, “We’re already doing digital.”
And they’re right.
The problem is that doing digital marketing and having a digital growth strategy are two very different things.
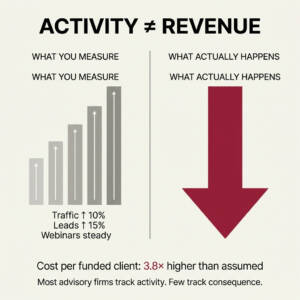
Activity is not the same as growth
Take a look at everything happening across a typical financial services firm.
Marketing is producing content and campaigns, someone is responsible for the website, sales or business development is following up with prospects, and the CRM is collecting information. An agency may be managing advertising and leadership is looking at reports showing website traffic, leads, email opens and other metrics.
There can be an enormous amount of activity.
But I like to ask a much simpler question:
How much new business is your digital channel actually generating?
That question is surprisingly difficult for many firms to answer.
And that’s usually a sign that there is a bigger issue.
Nobody owns the entire journey
One of the biggest digital growth challenges I see isn’t a lack of effort, it’s fragmentation. Different people own different pieces of the customer journey:
- Marketing owns awareness
- The website team owns the website
- An agency owns paid media
- Sales owns the prospect once someone raises their hand
- Operations owns onboarding
- Technology owns the systems connecting everything
Everyone can be doing their individual job well while the overall system still underperforms.
That’s because prospective clients don’t experience your organization in departments, they experience one journey.
They discover you, they research you, and they compare you with alternatives.
They visit your website, they read your content, and they may encounter you several more times before they’re ready to talk. But eventually, they reach out.
The question is whether you’ve intentionally designed that journey or whether it simply developed over time.
A good website isn’t a digital strategy
This distinction is especially important in financial services.
A firm can spend a significant amount of money redesigning its website and still generate very little business from it. The website might look great, it might accurately explain the firm, and it might even attract traffic.
But what happens next?
Does the content answer the questions prospects are actually asking?
Does the site establish a compelling reason to choose your firm?
Are there clear conversion paths for visitors who aren’t ready to schedule a meeting today?
Do you know where your highest-value prospects are coming from and are those prospects being nurtured?
Can you see which marketing activities eventually become opportunities and revenue?
If the answer to several of those questions is no, redesigning the website again probably isn’t the answer. The problem is bigger than the website.
The same applies to marketing
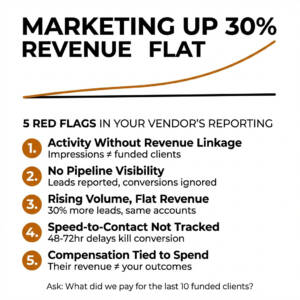
More marketing isn’t necessarily the solution either.
This is where firms can waste a lot of money.
Traffic isn’t the goal, clicks aren’t the goal, impressions aren’t the goal, even leads aren’t ultimately the goal.
The objective is profitable growth.
That doesn’t mean those other metrics aren’t useful as they absolutely are. But they should tell you something about progress toward a business outcome.
The real opportunity is connecting the pieces so you can understand what’s working, what’s getting in the way, and where the next dollar or hour should be invested.
Five questions worth asking
If you’re an RIA or leading a community bank, credit union, or other financial services firm, I’d start with five questions:
- Can we clearly explain how digital contributes to new revenue?
- Do we know which digital investments are actually influencing new business?
- Is someone responsible for the entire digital customer journey, rather than individual pieces of it?
- Do marketing, sales, technology and customer experience share the same definition of success?
- If we had another $100,000 to invest in growth tomorrow, would we know where to put it and why?
You don’t need perfect answers.
But if those questions create a lot of discussion in the leadership room, that’s useful information.
This is where digital growth strategy starts
I don’t believe most smaller financial firms need more marketing activity for the sake of activity, they need more clarity.
What are we trying to accomplish? Where are the biggest opportunities? What’s preventing prospects from moving forward? What should we stop doing? What should we invest more heavily in?
And most importantly, how will we know if it’s working?
Once those questions are answered, the website, content, SEO, advertising, CRM, automation and technology all become tools supporting a larger strategy.
That’s when digital starts becoming more than a marketing channel, it becomes part of how the business grows.
And for financial firms that already have something incredibly valuable: trust, reputation and strong client relationships – there’s often much more digital growth potential sitting there than leadership realizes.
The opportunity isn’t necessarily to reinvent the business, it’s to make the business you’ve already built easier to discover, easier to understand and easier to choose.